


Spectrum Credit’s recognition at the Inclusive Finance Industry Awards (IFIA) 2026 reflects a model built around specialised products, productive lending, disciplined risk management and an increasingly digital customer journey
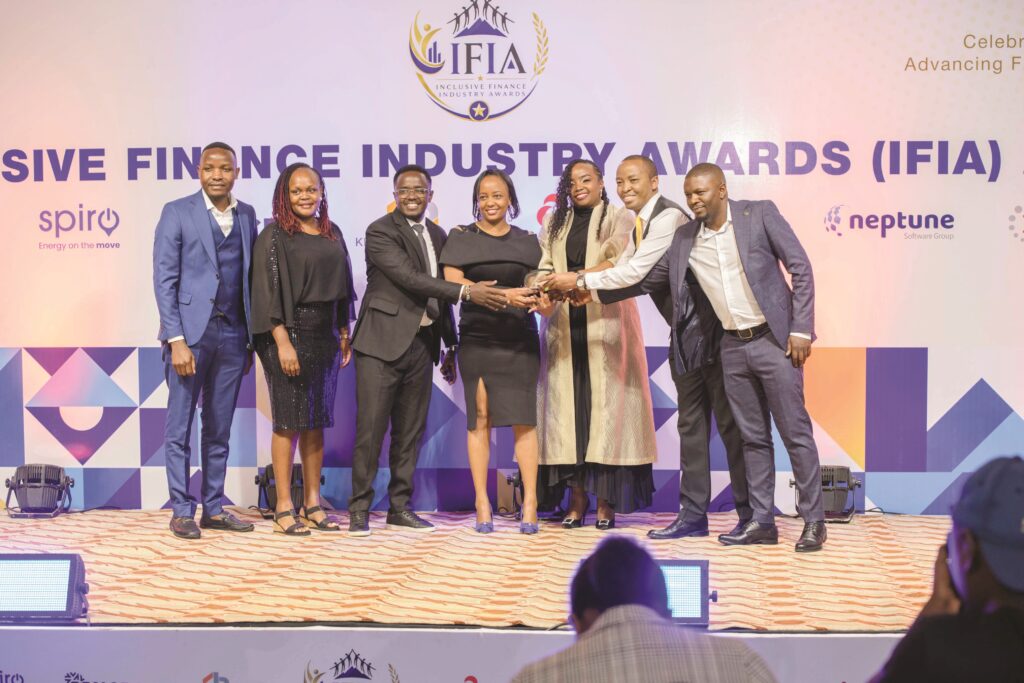
For Spectrum Credit, recognition at the Inclusive Finance Industry Awards (IFIA) 2026 is closely tied to the way the institution has built its business. Named Second Runner-Up in the Best Education Finance Initiative and Second Runner-Up in the Best SME Finance Initiative, the recognition reflects two areas in which the Kenyan fast growing microfinance institution has deliberately developed products around specific financing gaps.
The awards come as Spectrum Credit undergoes a significant transformation in scale. Established in 2011, the institution now has more than 900 employees, over 155 branches across the country and a presence in every county, alongside a portfolio of over ten products, five of which form its major commercial focus.Yet the institution’s growth is not being measured only through branches, employees or the size of its loan book. Its strategy is rooted in financing economic activity, particularly among business owners who require capital to sustain and expand their enterprises.
“We don’t just lend, we empower,” says Mr. Edwin Nyamache, Head of Strategy and Executive Personal Assistant to the CEO and founder, Mr. Sam Jim Mwanyasi, describing a philosophy that sits at the centre of Spectrum Credit’s operating model.
Education finance designed around a real gap
The Second Runner – Up recognition in the Best Education Finance Initiative is underpinned by Spectrum Credit’s Go Study Abroad Loan product, or SAL. This is a specialised product designed around the financing requirements of Kenyan students and families pursuing education overseas.
The product emerged from a financing gap that Spectrum Credit identified in the education market. Students travelling abroad must meet a range of requirements, including demonstrating that their parents or sponsors have the financial capacity to support their education. Spectrum Credit developed a financing structure specifically around that need, providing resources to students and parents while also extending support beyond the initial departure.
The product has grown from what began as a relatively small operation into a recurring financing line. Spectrum Credit currently supports more than one hundred students every month, with average monthly disbursements of approximately Kshs. 300,000 to Kshs. 400,000.
Its significance lies in its specialization. Rather than treating education finance simply as another consumer lending category, SAL was developed around a defined customer journey and a specific financial requirement.
Mr. Nyamache describes it as one of the company’s bespoke products and notes that Spectrum Credit was among the pioneers of financing solutions specifically structured around students seeking opportunities to study abroad. The lender has also been able to continue supporting families after students leave the country, particularly where parents have assets that can support further financing.
From small loans to an SME finance platform Spectrum Credit’s Second Runner-Up recognition in the Best SME Finance Initiative reflects a broader institutional evolution.The company began with small, unsecured loans. Over time, it expanded into more structured commercial financing, including local and import financing, asset financing and trade finance for contractors. The progression has allowed the institution to move from a conventional microfinance model towards a more diversified platform serving businesses with different capital requirements.
Its flagship logbook financing product, for example, provides a longer-term, secured financing option with limits of up to Kshs. 10 million. Alongside it are asset and import financing products that support businesses seeking to acquire assets or finance commercial requirements.
Trade finance extends this proposition further, with Spectrum Credit providing bid bonds, performance bonds and performance guarantees, particularly to contractors. These products position the institution within the wider financing requirements of businesses participating in the formal economy.
At the smaller end of the market sits Inuka, a short-term micro, small and medium enterprises (MSMEs) financing product providing loans of between Kshs. 3, 000 and Kshs. 70, 000, primarily to meet liquidity needs.The product has become a major driver of customer acquisition, particularly among small businesses operating in a daily cash-flow economy.
Where the business becomes the collateral
The central innovation behind Inuka is its relationship-based approach to customers who may have viable businesses but lack conventional collateral. Spectrum Credit’s starting point is physical onboarding. Customers are verified at their business premises, allowing the institution to establish that it is dealing with a legitimate business rather than extending a consumer loan that could be used for unrelated expenditure.
Many of the businesses targeted operate on a daily-income, daily-expense model. Inuka therefore allows for partial repayments, including daily payments, within a thirty -day loan cycle. Instead of waiting until the end of the month for a customer to produce a lump sum, the repayment structure allows him or her to service the facility progressively while continuing to operate the business.
Spectrum Credit has also deliberately avoided concentrating its approximately Kshs. 5 billion loan book in one product or sector. Its lending extends across transport, hospitality, tourism, consumer products and other business activities, while the portfolio combines secured lending with products designed for customers without traditional collateral.
The institution’s approach is based on the premise that access to finance should not automatically be restricted to businesses that already possess conventional security.
Risk management through relationship
Lending without traditional collateral requires a different approach to risk. Inuka’s initial onboarding is conducted physically at the customer’s premises. Each loan officer is paired with a collection officer, creating an additional layer of oversight. A verification team independently checks loans, while a broader risk team assesses whether facilities fall within agreed parameters.
Mr. Nyamache argues that the process can help customers develop financial discipline because they are effectively reconciling their business performance every day, accounting for loan repayments, stock requirements and other expenses rather than waiting until the end of a cycle.
Spectrum Credit’s field teams interact directly with businesses, provide financial-literacy support and advise customers as their enterprises develop. The institution sees presence and consistency as important elements in maintaining repayment behaviour. “Their growth will always translate to our growth. And that is our approach,” Mr. Nyamache says.

Reaching women, youth and underserved businesses
The scale of Inuka has also created a measurable social and economic footprint. Among Spectrum Credit’s approximately 50,000 customers, more than 40,000 access Inuka. The institution’s internal data shows that approximately 80 per cent of these customers are women, while almost 70 per cent are youth.
The numbers demonstrate where small-ticket business finance is finding demand. For Spectrum Credit, this reinforces the idea that the financing gap remains substantial despite increasing competition within Kenya’s financial sector. The emergence of digital loan products Mr. Nyamache observes, has repeatedly demonstrated that new financial solutions can reveal additional gaps rather than exhaust demand.
The opportunity, therefore, is not necessarily an absence of competition. It is the continued presence of customers whose specific financing requirements have not yet been adequately addressed.
Physical reach meets digital scale
Spectrum Credit’s extensive branch network remains important to its relationship-led model, but the institution recognises that physical expansion cannot remain its only route to growth.Digital acceleration is now one of three strategic pillars alongside margin improvement and customer experience. More than 90 per cent of the institution’s processes have been automated, while USSD and application-based channels increasingly handle customers’ transactions.
Inuka demonstrates the hybrid model particularly well. Initial onboarding remains physical because the institution needs to establish the customer’s identity and business activity. Once that relationship is established, however, repeat loans, limit increases, statements and repayments can all be fully handled digitally. The shift allows Spectrum Credit to preserve the relationship-based foundation of its lending model while reducing the operational cost of serving repeat customers.
Its next stage of digital development is expected to go further, with greater use of data analytics, credit scoring, automated scoring and self-onboarding. The institution is also considering how its products can eventually extend beyond MSMEs and SMEs, to employed customers requiring financing. These products can be accessed through digital channels.

The people behindthe numbers
Behind Spectrum Credit’s expansion is a workforce that has grown alongside the business.In 2020, the institution had less than one hundred employees, ten branches and slightly below two thousand customers. Today, it has more than nine hundred employees, more than one hundred and fifty five branches. Its customers are approximately fifty thousand and this number is expected to grow to one hundred thousand by the end of 2026.
More than eight hundred employees spend about eighty per cent of their time in the field, supporting business development and maintaining customer relationships.
The institution’s stakeholder ecosystem also extends to customers, investors, government and industry regulators, including the Central Bank of Kenya. Each plays a pivotal role in creating the environment within which Spectrum Credit operates and grows.
The next stage
Spectrum Credit’s ambitions extend well beyond its current scale. The management projects that the loan book could reach Kshs. 15 billion within five years, with banking emerging as the potential next stage of institutional development as the business reaches greater scale. The lender’s philosophy remains anchored in the belief that capital can unlock economic opportunity. Additionally, its mantra, ‘capital today, transformation forever,’ captures that view, whether the capital is financing a student pursuing education abroad, helping an SME replenish stock or enabling a contractor to participate in a new project.
The IFIA- 2026 recognition therefore provides more than an awards milestone. It offers a snapshot of an institution in transition: from small unsecured lending to a diversified SME finance platform; from branch-led distribution towards a hybrid physical-digital model; and from serving a relatively small customer base to pursuing mass-market reach.
For Spectrum Credit, the measure of that transformation ultimately extends beyond the balance sheet. It lies in whether the capital reaches productive activity, whether businesses can grow, whether customers are treated with dignity and whether the institution can continue creating opportunities for the people who drive its own expansion.


