


Kenya’s financial inclusion agenda has traditionally focused on access: who can obtain credit, how quickly they can receive it, what collateral they can provide and whether financial institutions can reach customers who have historically remained outside the formal financial system. As the sector matures, however, access alone is becoming an increasingly incomplete measure of financial inclusion. The more important question is what that access enables the customer to achieve.
It is against this backdrop that JawabuBiashara Limited’s recognition at the 2026 Inclusive Finance Industry Awards (IFIA) takes on significance. The institution was recognised for its biogas lending solution in Kenya, placing its approach to agricultural and household finance within a broader industry conversation about responsible, innovative and impact-oriented lending.
For JawabuBiashara, the recognition is not simply about financing a clean-energy technology. It reflects a wider philosophy that underpins its lending model: credit should create tangible value for the borrower and strengthen their position beyond the life of the loan.
For Mr. Charles Njoroge, the founder and managing director of JawabuBiashara, the purpose of credit must ultimately be visible in the life of the customer. “Loans are not just loans. You should do loans where people can feel and touch the impact that loan has delivered.”
That philosophy provides an important lens through which to understand the institution’s IFIA recognition. The award gives visibility to a model that seeks to connect the financial transaction with a tangible asset and a practical improvement in the customer’s daily life.
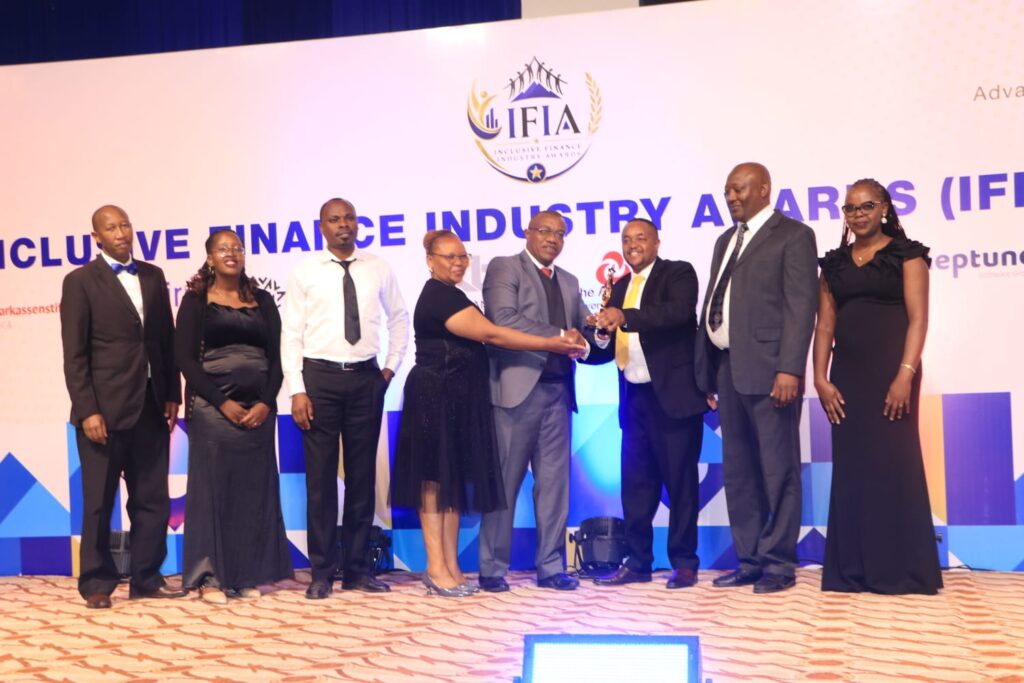
Jawabu Biashara team recieving an award for the 1st runners-up Most Innovative Financial Inclusion product during the IFIA 2026.
The story behind the recognition
Biogas financing has become one of the clearest expressions of JawabuBiashara’s approach to agricultural finance. For the institution, the significance of this intervention lies not only in the number of systems financed, but also in what the assets are intended to achieve. A biodigester provides an alternative source of household energy while making productive use of livestock waste. For farming households, it can therefore address an immediate energy need, while contributing to wider improvements in household resource management.
The model also illustrates how financial inclusion can intersect with broader social and environmental priorities. In households that depend heavily on firewood, sourcing fuel can consume significant amounts of time, particularly for women and girls. Traditional cooking methods can also expose households to smoke, while continued reliance on firewood places additional pressure on natural resources. By financing biodigesters, JawabuBiashara is seeking to make clean-energy technology more accessible while connecting the financing to a practical household need. The result is a financial product whose value extends beyond the original transaction.
That principle extends beyond biogas. JawabuBiashara also finances water tanks, chaff cutters and solar pumps, among other productive assets. Each addresses a specific constraint within the farming or household economy while providing an asset that remains with the customer.
Making the farmer bankable
Agriculture remains one of the more challenging segments of the credit market because its economic cycles do not always fit conventional lending models. A trader or small retailer may generate transactions every day, allowing a lender to develop a relatively clear picture of cash flow. Farming is less predictable. Income is often seasonal, production is exposed to weather conditions and commodity prices can change significantly between the time a farmer invests in production and when the crop reaches the market.
JawabuBiashara’s position, however, is that these risks should not automatically make farmers unbankable. Instead, they require lenders to develop a deeper understanding of the economic activities that generate the customer’s income and to structure financing around genuine productive needs. This is where the institution’s asset-based model becomes particularly relevant. Rather than relying entirely on conventional collateral, JawabuBiashara finances assets that serve a direct purpose for the borrower and can subsequently form part of the security for the facility. The approach is designed to address a longstanding barrier in agricultural finance: farmers may have productive enterprises and assets but lack the conventional collateral required by many lenders.
By linking the loan to a productive asset, the institution seeks to address both sides of the equation. The farmer gains access to something that can strengthen the enterprise, while the lender has greater visibility into the purpose and underlying value of the financing. The model is not without risk. Mr. Njoroge acknowledges that agricultural lending remains challenging because many of the factors affecting a farmer’s ability to repay are outside the direct control of both the lender and borrower.
Yet it is precisely this complexity that makes the approach relevant to the wider financial-inclusion debate. If underserved farmers are to participate meaningfully in formal finance, lenders may need to move beyond rigid models of risk assessment and develop products that reflect the realities of agricultural livelihoods.
When finance changes the household
The impact of this approach becomes clearer when viewed through the experience of individual customers. One of the cases shared by JawabuBiashara is that of Jane Mwangi of Gachirero village in Mukurweini, who received financing support to install a biogas system at her home. Before the installation, Mwangi relied on firewood and experienced eye irritation from smoke. With the biogas system in place, she began using the gas for cooking as well as heating water for bathing and washing clothes. The system has also reduced her dependence on firewood, easing one of the challenges associated with obtaining dry fuel during rainy periods.
For Mwangi, the value of the financing is therefore not expressed primarily through the loan itself. It is reflected in the asset now embedded in her household and the practical benefits it provides every day. Her experience also demonstrates how the impact of a financial product can extend beyond the original borrower. Mwangi says visitors to her home have seen the benefits of the system, prompting her to introduce several other people to JawabuBiashara.
The example provides a useful illustration of JawabuBiashara’s transformative lending. The financial transaction creates an asset, the asset addresses a genuine need, and the resulting experience can influence other members of the community. For a sector increasingly concerned with meaningful financial inclusion, that is an important distinction.
Building the capacity behind the loan
Financing the right asset is only one part of the equation. Customers also need the knowledge and capacity to manage their businesses and make effective use of the capital available to them.
Customers who understand how to manage costs, plan for challenges and operate a viable enterprise are better positioned to remain financially healthy and meet their obligations. For the lender, customer success therefore contributes directly to portfolio quality and long-term relationships. As Mr. Njoroge puts it : “Their success is really our success.” JawabuBiashara’s model is based on the belief that sustainable lending requires more than simply putting money into the market.
Financing resilience
Although biogas is at the centre of JawabuBiashara’s IFIA recognition, the institution’s wider asset-financing model also points towards an emerging role for finance in building agricultural resilience. Water tanks, solar pumps and other productive assets can help farmers respond to some of the operational challenges associated with water availability, energy costs and changing weather patterns.
For farmers, resilience is often defined by practical questions: whether there is enough water for production, whether energy is affordable and reliable, whether livestock operations can remain productive and whether a household can withstand an unexpected disruption. Finance can play a role in addressing these constraints when products are designed around the specific assets customers need.
JawabuBiashara’s approach suggests that climate and resilience financing does not always have to begin with large-scale infrastructure. At household and farm level, smaller productive assets can also strengthen economic resilience when they are accessible through appropriate financing.
A year of validation
For JawabuBiashara, the IFIA recognition has come at a significant point in its institutional development. In 2026, the company also obtained its Central Bank of Kenya Digital Credit Provider ( DCP) license, which Mr. Njoroge views as an important indication of regulatory acceptance and institutional credibility. For a relatively young financial institution operating in a market where trust is critical, the licence represents more than a regulatory milestone. It provides an important foundation for the institution’s next stage of growth.
The IFIA recognition adds another layer of validation. It demonstrates that the organisation’s work is beginning to attract attention within the wider inclusive-finance sector and gives greater visibility to a model built around specialised agricultural and clean-energy finance.
The challenge of being small
Kenya’s finance sector market is dominated by institutions whose names are immediately familiar to consumers. For a younger player, the first challenge is often explaining who the institution is before communicating what it offers. Mr. Njoroge identifies this as a significant challenge for JawabuBiashara. The institution must build awareness of its brand while simultaneously educating the market about its business model and value proposition. Trust is equally important.
Additionally, the wider microfinance sector has faced criticism over pricing and debt-collection practices, creating a reputational environment in which newer institutions must work deliberately to address in a bid to enhance credibility. He says the decision to establish JawabuBiashara was partly driven by his conviction that microfinance could be delivered differently.
From recognition to 2030
JawabuBiashara’s next phase is guided by its Strategic Plan 2030, which provides a roadmap for expanding its geographical reach and strengthening its position within Kenya’s microfinance sector.
A model built around field interaction, customer education, productive assets and specialised agricultural knowledge becomes more demanding as geographical coverage increases. Growth will require capital, technology, strong risk-management systems, capable employees and strategic partnerships. It will also require JawabuBiashara to maintain the trust it is seeking to build. By 2030, Mr. Njoroge is looking forward to JawabuBiashara becoming a household name in Kenya’s microfinance sector and move from being recognised as an emerging player to becoming a leading institution in its space.
The customer behind the credit
Mr. Njoroge’s understanding of the customer extends beyond the borrower. He describes JawabuBiashara as having two customers: the internal customer, represented by employees, and the external customer, represented by borrowers. The distinction reflects his belief that customer experience begins within the institution itself. Employees need to understand the organisation’s purpose and the realities facing its customers if they are to provide the quality of support the business promises.
Following the IFIA recognition, Mr. Njoroge’s message to employees is therefore one of shared ownership. The recognition belongs to the team as much as it belongs to the organisation, he says, while the next responsibility is to build on it. To customers, his message is equally centred on partnership. JawabuBiashara intends to continue investing in capacity building, innovation and engagement while remaining receptive to customer feedback. The philosophy is straightforward: when customers succeed, the institution has a stronger foundation for sustainable growth.
What the recognition really signals
The IFIA recognition ultimately raises a broader question for Kenya’s finance sector: what should successful financial inclusion look like? Access to credit remains essential, but access alone does not guarantee transformation. The more important consideration is what happens after the financing reaches the customer.
Jawabu Biashara is attempting to answer these questions through a model that places the purpose of finance at the centre of the lending relationship. Its biogas financing provides the clearest example. The financing results in an asset with continuing utility, one that can address a household need while also contributing to the institution’s broader approach to agricultural and inclusive finance. That is the story behind the recognition.
It is also the proposition JawabuBiashara is taking into the next stage of its development: that the future of inclusive finance may depend not only on making credit available, but on designing financial products around what customers need to become more productive, resilient and economically secure. The award has provided recognition. The CBK licence has strengthened the institution’s formal standing. The 2030 strategy now presents the next test. For Jawabu Biashara, the real measure of success will ultimately be whether the financing it provides leaves customers stronger than it found them.
For the farmer, that could mean a productive asset that continues to generate value long after the repayment period. For a household, it could mean cleaner and more reliable energy. For an entrepreneur, it could mean the knowledge and financial capacity to navigate another challenging business cycle. That is what gives JawabuBiashara’s IFIA recognition significance beyond the award itself.


