


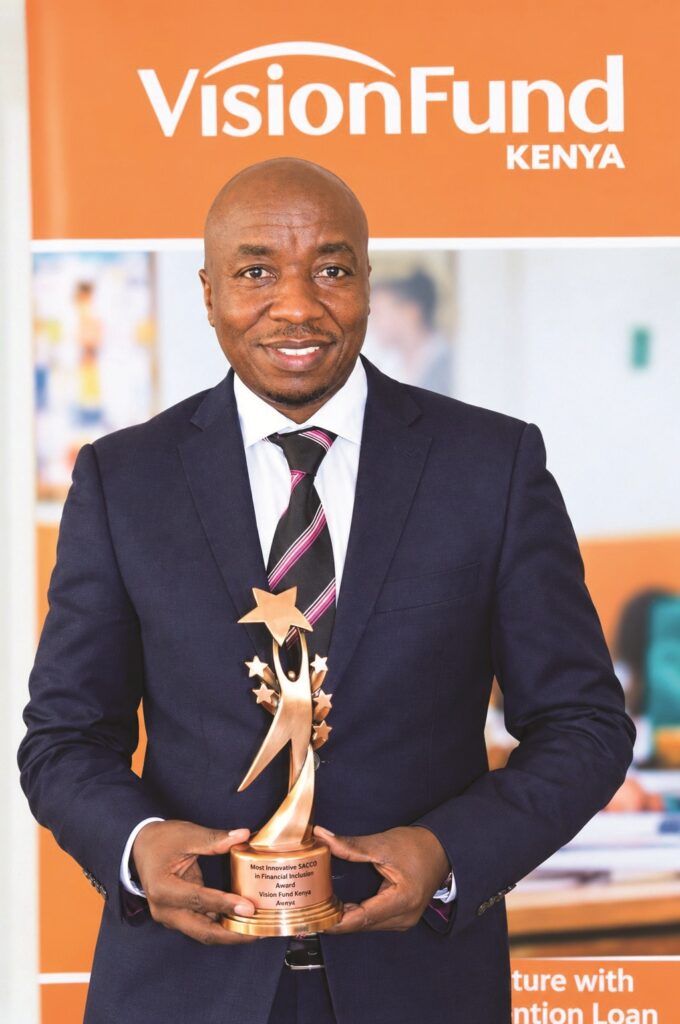
Recognized at the inaugural Inclusive Finance Industry Awards for Most Innovative Product, VisionFund Kenya is demonstrating how financial innovation can extend beyond conventional lending to reach underserved communities with credit, resilience solutions and financial literacy. Its FAST model, climate-linked income protection and deliberately layered approach to finance are designed to help vulnerable households move from financial exclusion towards greater income, assets and resilience
Financial inclusion is often measured through the expansion of access: how many people can open accounts, obtain credit or participate in the formal financial system. But for communities living in some of Kenya’s most vulnerable and marginalised areas, the more important question is what happens when finance finally reaches them.
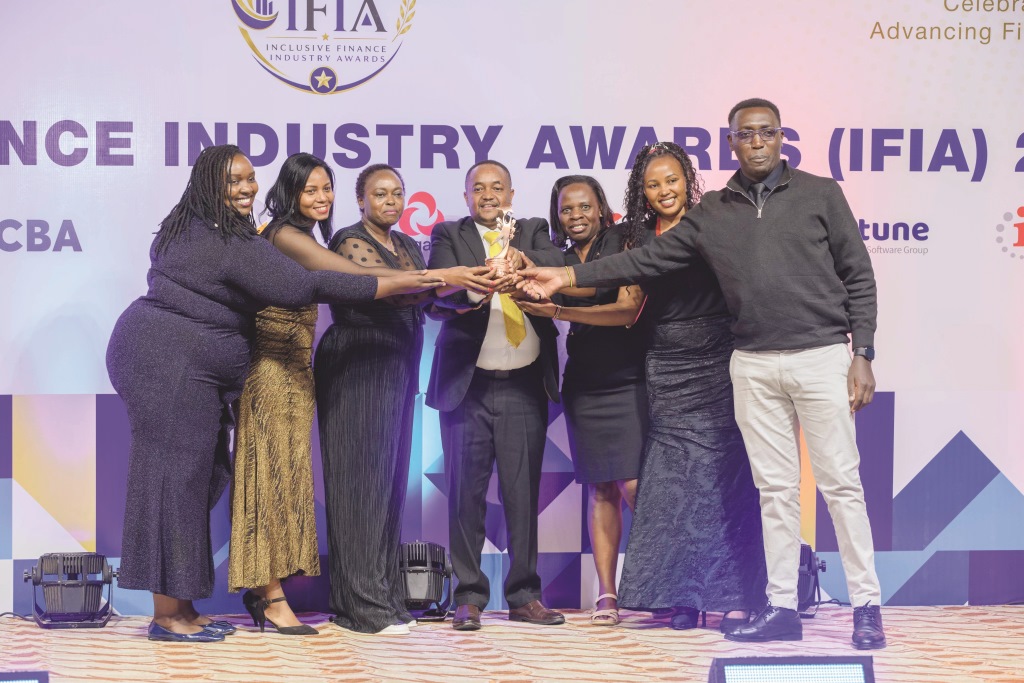
For VisionFund Kenya, the answer is increasingly centred on whether financial products and services can strengthen livelihoods, create income and jobs, build resilience and give households the capacity to progress. That philosophy sits at the heart of the lender’s recognition at the inaugural Inclusive Finance Industry Awards – 2026 organized by AMFI-K, where VisionFund Kenya clinched the Most Innovative Product award. Mr. Reuben Mwaura, CEO, VisionFund Kenya avers this recognition represents confirmation that financial solutions designed around the realities of underserved customers can create meaningful outcomes.
VisionFund Kenya is a microfinance institution founded by World Vision and it operates as part of a wider global network. Regulated by the Central Bank of Kenya (CBK) as a digital credit provider, it operates across more than thirty counties with a focus on underserved communities. Its operating philosophy is straightforward: understand the customer’s underlying challenge first, then structure the financial solution around that reality. “We pride ourselves in working with the customers to identify the core pain that they are going through and we structure solutions that address their current day-to-day realities,” says Mr. Mwaura.
Moving savings groups into formal finance
The product at the centre of VisionFund Kenya’s IFIA recognition is Finance Accelerating Savings Group Transformation (FAST), a model designed for savings groups seeking to move towards greater access to formal financial services.
Rather than lending directly to individual members, VisionFund Kenya funds the group’s collective structure, or “box”, allowing the group to continue lending to its members. That distinction enables the institution to work with an existing community-based financial mechanism while introducing additional capital and a clear pathway towards formal finance.
The model is already deployed in highly vulnerable locations. In Baringo County, for example, VisionFund Kenya operates in two areas that are facing significant insecurity. Working alongside World Vision Kenya on training and equipping communities, VisionFund Kenya brings social and financial interventions together at the local level. Strategic partners prepare communities and establish savings groups, after which the lender provides the mechanism for those groups to access formal capital. As a result, several group members have graduated into taking loans independently, transitioning from collective savings to formal financial participation.
From Credit to Resilience
VisionFund Kenya’s innovation extends beyond providing capital. Another key solution, Climate Cash, addresses the financial vulnerability caused by weather-related shocks. In the recent past, following a period of excessive rainfall and flooding, the institution worked with partners providing real-time weather data to develop an income-replacement mechanism that responds when weather conditions disrupt livelihoods.
This represents an important evolution in financial resilience. For households dependent on climate-sensitive agriculture, a product responding to weather disruption addresses a fundamentally different problem than conventional credit, protecting the income-generating capacity that makes long-term progress possible.
This resilience focus aligns with VisionFund Kenya’s broader approach to measuring impact. Rather than focusing solely on disbursement volumes, the institution tracks whether customers increase incomes, build assets, and create employment. This lens extends directly to children, reflecting the clear link between household economic stability and children’s education, health, and protection.
Finance alone is not enough
A defining element of VisionFund Kenya’s model is layering financial products and services with education. The institution provides financial-literacy programme alongside its product offering, based on the principle that credit alone does not create sustainable livelihoods.
This philosophy is developed through its Empowered Worldview programme, which focuses on mindset and identity, encouraging customers to examine and leverage their existing resources before borrowing. In some instances, Mr. Mwaura notes, customers completed the training and realized they could first optimize existing resources without taking a loan—an outcome VisionFund Kenya views as a positive reflection of responsible financial inclusion.
Scale Without Compromising Portfolio Quality
VisionFund Kenya’s inclusive model is underpinned by rigorous portfolio discipline. While the microfinance sector averages a portfolio-at-risk (PAR) between 12 and 15 per cent, VisionFund Kenya’s FAST solution maintains PAR below 2 per cent on an outstanding portfolio exceeding US$1 million.
Because FAST is entirely unsecured, performance relies on disciplined underwriting and strong field relationships rather than aggressive collections. Frontline credit officers build deep trust—often earning the moniker mwalimu (teacher) for their advisory support. Furthermore, consumption lending is capped below 10 per cent, concentrating capital on productive agriculture and small enterprises with clear livelihood impact.
Mr. Mwaura encapsulates this operational rigor succinctly: “We target right, we train right, we appraise right, and we do monitoring in the right way.”
The human economics of a Kshs. 20,000 loan
Let’s output the result directly. The practical value of VisionFund Kenya’s methodology is best reflected in the human economics of its borrowers. During a field visit, Mr. Mwaura documented a customer who joined a local savings group and accessed an initial facility of Kshs. 20,000. She deployed the capital across multiple productive channels: launching a vegetable enterprise, leasing land, purchasing agricultural inputs, and settling school fees.
After harvesting six bags of maize and fully repaying the loan, the broader impact of the facility emerged. Previously unable to contribute to her church offering due to financial hardship, her new income stream enabled her to participate, restoring a deep sense of personal dignity and community standing.
For VisionFund Kenya, this case illustrates that inclusive credit extends beyond capital allocation. The true objective is to build an ecosystem where capital becomes productive, supported by the training and structure necessary for customers to achieve lasting financial success.
Regulation, technology and the “Phygital” model
VisionFund’s strategic evolution aligns with Kenya’s dynamic regulatory landscape. Central Bank of Kenya (CBK) licensing provides the regulatory clarity needed to scale digital capabilities while reinforcing consumer protection, data privacy, and debt sustainability.
The institution operationalizes this through a “phygital” model—seamlessly integrating digital infrastructure with physical touchpoints. Digital channels eliminate geographical barriers in remote markets, while local field staff preserve the human relationships essential to consumer trust and responsible lending.
Building Towards 2030
Looking ahead to 2030, VisionFund Kenya projects serving nearly 150,000 customers in vulnerable communities and reaching approximately 500,000 children. Achieving this scale requires maintaining a deliberate balance: expanding access while safeguarding portfolio quality, deepening climate resilience, and keeping financial solutions anchored in tangible economic needs.
Central to this trajectory is VisionFund Kenya’s partnership model. By leveraging its connection with World Vision and local organizations, the lender provides the financial infrastructure required to transition informal savings groups into larger capital pools and formal banking channels.
Ultimately, VisionFund Kenya’s IFIA recognition for Most Innovative Product reflects purpose-built financial architecture rather than novelty. FAST connects savings groups to institutional capital, Climate Cash mitigates weather shocks, Empowered Worldview provides financial literacy, and a “phygital” delivery model scales reach while preserving field relationships.


