From a modest business-finance facility to a specialised education-finance model, Premier Credit has built an approach that combines capital, capacity building and measurable educational outcomes, a strategy that earned it the Best Education Finance Initiative (1st runner up) at IFIA-2026
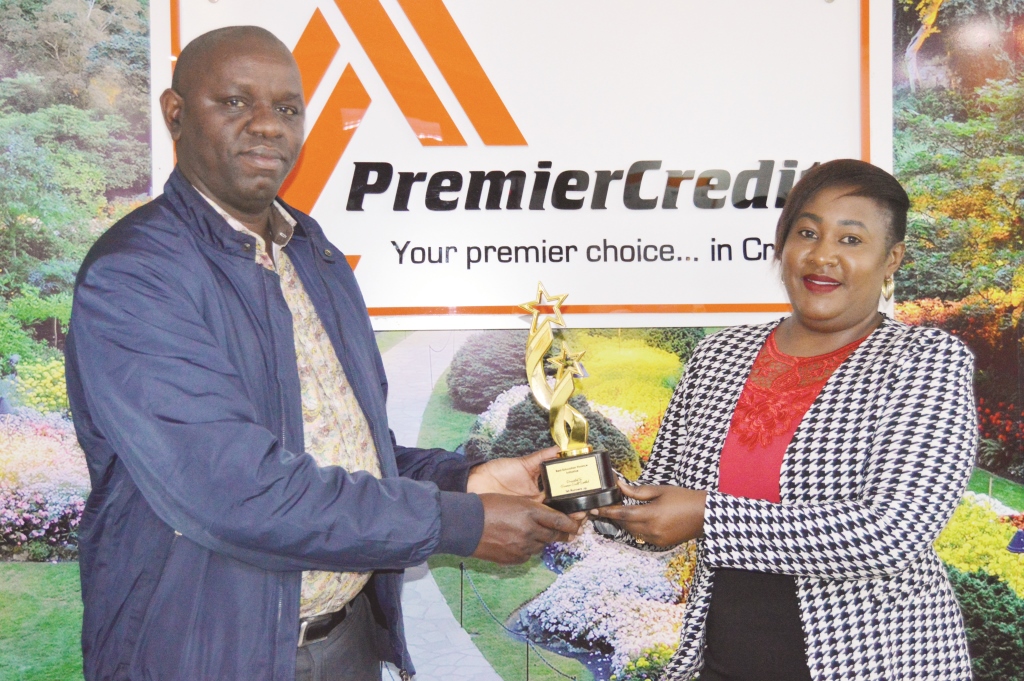
When Premier Credit was named the Best Education Finance Initiative ( 1st runner up) at the Inaugural Inclusive Finance Industry Awards 2026, the recognition brought into focus a financing model built around a challenge that has long confronted many private schools: having a viable institution does not necessarily mean having access to appropriate credit.
For Premier Credit, the response has been to design financing around the realities of the schools themselves rather than treating them simply as conventional business borrowers. The model began modestly in 2022, when Premier Credit was financing schools through a general business facility, with amounts starting at about Kshs. 20,000 and Kshs. 30,000. No security was required in the early stages. By 2024, the lender had recognised the scale and specificity of the opportunity and hence transformed the facility into a dedicated school-finance product.
That evolution has since extended beyond lending. Premier Credit now combines financing with management and financial-literacy training, infrastructure and asset finance, partnerships, and interventions designed to track educational outcomes. It is this combination of access to capital and capacity building that has shaped the institution’s education-finance proposition.
For Pauline Wangari Njue, Head of School Product at Premier Credit, the starting point was a financing gap she says was visible across the market.“We realised that most of the schools were being discriminated against by mainstream lenders because of their low capacity and lack of collateral,” Pauline says. “We therefore decided to tailor-make a product that could serve these private schools, because they needed funding to improve both their education offering and structures.”
From a financing gap to a specialised product
Many of the private schools Premier Credit sought to serve had limited income and few of the conventional forms of collateral required by mainstream lenders. Yet their financing needs were furniture and learning materials, classrooms, laboratories, playgrounds and other infrastructure. The institution therefore adopted a deliberately accessible starting point. Its school – finance product ranges from Kshs. 20, 000 to Kshs. 5 million, allowing it to engage schools at different stages of their development.
Pauline says Premier Credit has funded more than four thousand schools since launching the product. Some of these institutions, she explains, have grown alongside the financier, progressing from small, emerging schools into more established institutions with improved infrastructure and increased learner capacity. The product was formally repositioned in 2024, when Premier Credit began treating education as a specialised financing segment rather than simply another category within its wider business portfolio.
Consequently, it started financing purchase of school furniture, stationery, books and games equipment as well as facilities like classrooms, science laboratories and computer laboratories. The objective was to address the multiple capital requirements that determine whether a school can expand and accommodate more learners.
“We decided it should be a product on its own, focusing on schools rather than simply treating them as another business,” Pauline explains. “We went to the ground and marketed it as a school-focused product, making sure we touched everything within the school and funded what met the school’s needs.”
Finance and Capacity
The product’s evolution also revealed another challenge: providing finance without helping school owners develop the capacity to manage it effectively could limit its impact.
James Kinyanjui, Assistant Head of Operations at Premier Credit, says many of the schools they target operate in informal areas of major towns and cities. Their directors may be entrepreneurs rather than education professionals, with qualified head teachers and teachers responsible for academic operations. One consequence of that model was that personal and school finances could become intertwined.
Premier Credit therefore incorporated financial literacy and management training into its engagement with school directors, helping them distinguish personal finances from school finances, understand financial management and improve the way they operate their institutions.“We wanted to build their capacity first in terms of management skills and financial literacy, and help directors understand how to run these businesses professionally, including separating personal finance from business finance,” Kinyanjui says.
To this end, the lender has worked with training partners including Dignitas, Edu-Plus and Strathmore University. Through one of its training engagements, more than 2,000 directors were trained, with subsequent programmes continuing to focus on school management, financial literacy and strategies for running sustainable school businesses.
The approach recognises that the financial health of a school depends on more than access to credit. Directors also need to understand how to collect and manage school fees, generate additional revenue and navigate periods when schools are closed and fee income slows.
Premier Credit has therefore trained school owner managers on establishing alternative revenue streams including: school canteens, transport and recreational facilities like swimming pools. It has also addressed the realities of parents whose incomes are earned daily rather than received as a single monthly salary. Directors have been trained on ways of accommodating parents who may need to spread school-fee payments over time.
Financing a school’s full development cycle
Premier Credit has continued expanding the product around the operational needs identified within the sector. Kinyanjui says the institution now provides asset financing for school buses, including new and second-hand vehicles, alongside working capital and partnership-based solutions. A development facility supports projects such as classrooms and laboratories, land acquisition and motor-vehicle purchases.
Initially, the product was designed around monthly payments. But Premier Credit found that this did not always correspond with the way schools generate revenue, since their cash flows are largely tied to academic terms.“We realised that the cash flow for schools is based on the term rather than the month,” Kinyanjui says. “We therefore introduced a term-based facility to accommodate schools, particularly during periods when they close for the long holiday.”
That adjustment illustrates the philosophy behind the product: financial inclusion is not simply about making credit available. It also requires the financing structure to reflect the economic realities of the customer.
Measuring what the financing achieves
Through Premier Credit’s partnership with Innovation, Development, and Progress (IDP), a US-based funder, the lender was able to launch the Incentive for Learning (IFL) program. The initiative is designed to assess academic performance and track where a school begins and how it progresses, while providing comparisons with schools within the same surrounding area.
Pauline says the programme began last year in October, with more than one hundred and fifty schools initially brought on board. The assessment focused on learners from grade one to grade six, examining reading, writing, mathematics and English among other areas.
Seventy-five schools qualified for the programme, after which assessments were conducted in February. Forty-one schools subsequently qualified for rewards, with the highest-performing school receiving Kshs. 100,000 from Premier Credit. The incentive was designed to encourage school directors to look beyond the commercial performance of their institutions and pay greater attention to educational quality. “We wanted to make sure the director does not concentrate only on the business, but also looks at the quality of education being offered to the children,” Pauline says.
The rewards could also be applied towards outstanding loan obligations, linking educational performance with tangible financial support. For Premier Credit, it creates a model in which the lender’s relationship with a school extends from the initial financing decision to the outcomes that financing is intended to support.
A broader institutional footprint
The education initiative forms part of a wider Premier Credit operation that, according to Pauline, began in 2014. The institution has 101 branches across the country, with operations also extending to Uganda, Tanzania, Zambia and South Africa, while expansion into the Democratic Republic of Congo (DRC) is planned. Pauline says Premier Credit currently has approximately 350,000 active clients and a workforce of about 2,500 employees. The appointment of Pauline as Head of School Product reflected the recognition that schools have distinct financial and operational requirements.
Premier Credit has also invested in training its own employees to better understand and serve the segment. Through a partnership with Opportunity International, more than forty staff members had been trained at the time of this interview (September), alongside fifteen managers. The institution plans to extend this training to more branch managers and increase the number of staff equipped to handle education finance.
Premier Credit is also training its teams to understand the needs of private technical and vocational training (TVET) colleges, which Pauline describes as another area with financing gaps similar to those initially identified among private schools. The objective is to understand what these institutions require to expand, increase coverage and bring more students into their programmes.
The next frontier
Pauline says Premier Credit is targeting to grow the education loan book to Kshs. 300 million, with TVETs expected to provide an additional avenue for growth. But the longer-term proposition is broader than the size of the loan book. For Kinyanjui, the value of the model lies in whether financing contributes to stronger schools, improved infrastructure and better outcomes for learners. “We are not only interested in financing the school so that we can make profits,” he says. “We are also concerned about the welfare of the learners and their academic output.”
What began in 2022 as relatively small business financing for schools has developed into a specialised model built around the full development cycle of an education institution. Capital remains central, but it is supported by management training, financial literacy, infrastructure finance, asset financing, partnerships and tools to measure educational progress.
The result is a financing proposition that recognises schools as more than borrowers. They are businesses that need to remain financially viable, institutions responsible for educating children and, in many communities, critical avenues through which families access education.
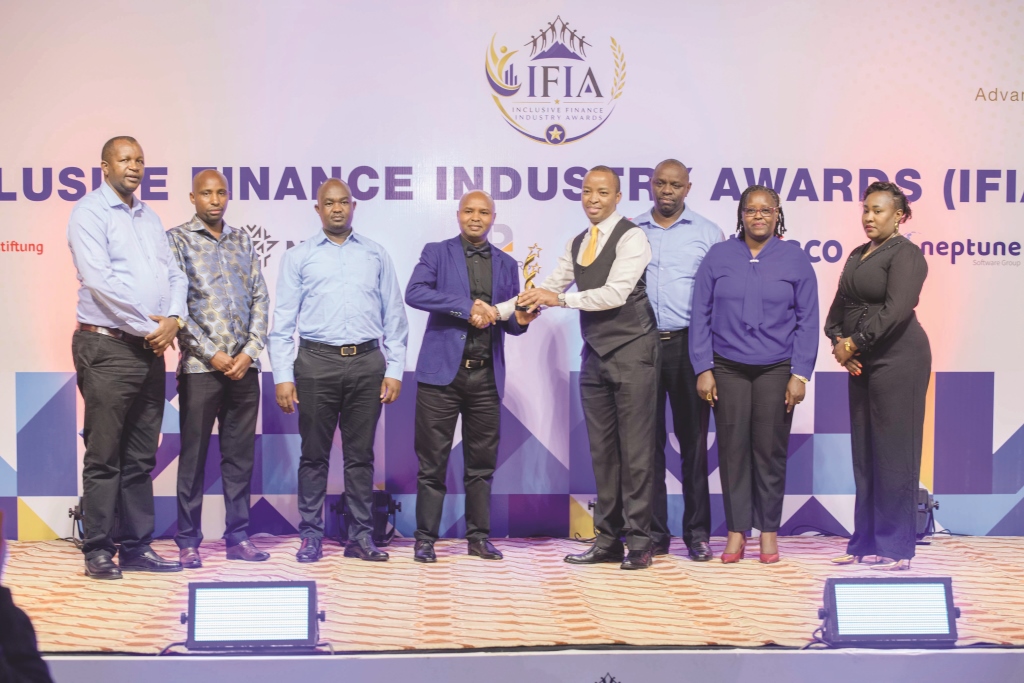
The IFIA recognition provides a marker of how far the initiative has evolved. Its more consequential test, however, lies in what happens beyond the trophy. This is whether more schools can access appropriately structured capital, strengthen their institutions, enhance learners’ capacity and ultimately provide better educational opportunities to the communities they serve.