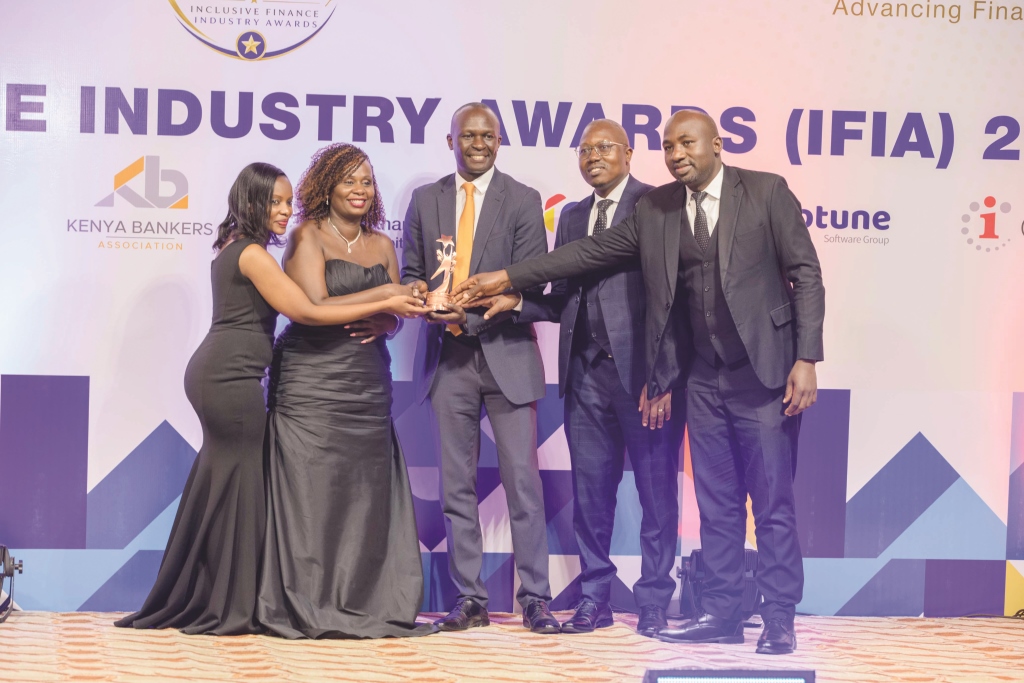
The most meaningful measure of financial inclusion is no longer simply whether people can access a financial institution. It is whether that access gives them the capacity to build, transact, withstand shocks and ultimately grow. This philosophy earned Faulu Microfinance Bank (MFB) the Best SME Finance Initiative award at the inaugural Inclusive Finance Industry Awards (IFIA) 2026. For an institution built on serving micro, small and medium enterprises (MSMEs), the accolade reflects a core evolution: designing financial solutions around the operational realities of the businesses receiving them.
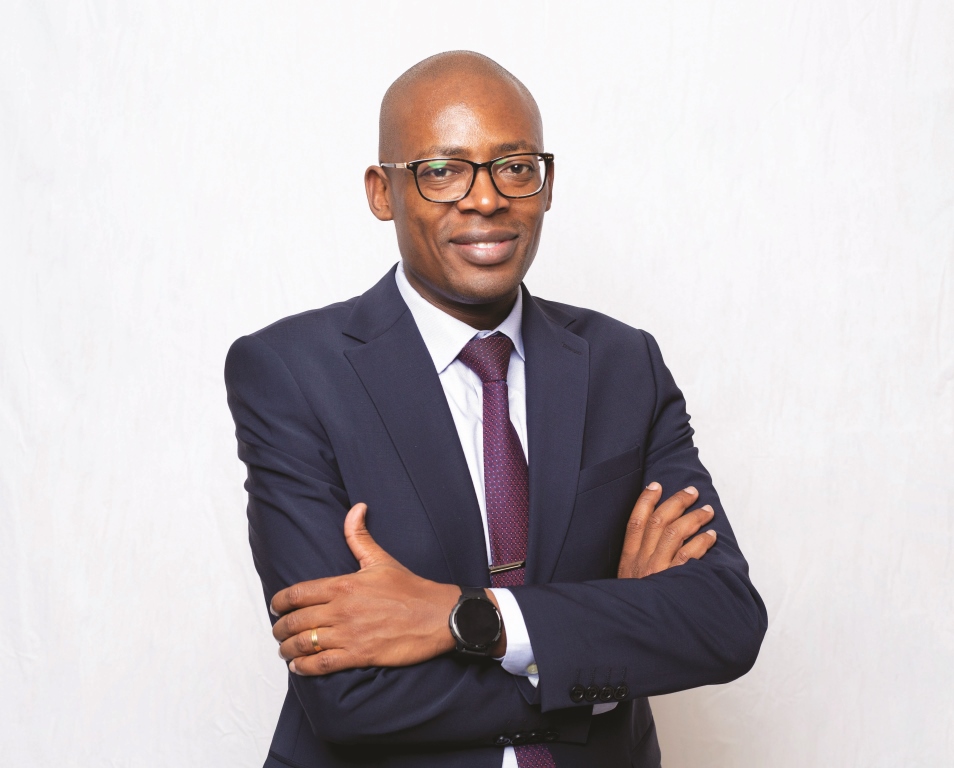
“There is a difference between inclusion and empowerment,” notes Mr. Julius Ouma, CEO and Managing Director of Faulu Microfinance Bank. “Access opens the door, but empowerment equips entrepreneurs with the resources, knowledge, and systems to succeed.”
This approach anchors Faulu MFB’s strategic ambition to become one of Kenya’s leading digital MSMEs lenders, integrating credit with digital infrastructure, financial literacy, transactional solutions, and post-disbursement support.
A Broader MSME Proposition
Faulu MFB differentiates its proposition by looking beyond capital disbursement to engage customers across the entire credit lifecycle. According to Mr. Ouma, the lender positions itself as an accessible partner dedicated to financial education, responsible borrowing, and sustained advisory support.
This engagement model incorporates institutional transaction services once reserved for large corporations. By upgrading its payment collection and internet banking platforms, Faulu MFB provides small enterprises with bulk, individual, and automated payment processing capabilities.
The rationale is clear. Capital alone does not address operational bottlenecks like payment collection, transaction reconciliation, or treasury management. By pairing credit with transactional tools, Faulu MFB ensures funded businesses possess the infrastructure needed to scale. Consequently, its “Best SME Finance Initiative” recognition at IFIA -2026 validates an approach that links capital allocation directly to operational growth.
Building a digital bank for the small business
Faulu MFB has revamped its core banking system alongside upgrades to its mobile, USSD, and internet banking channels. The lender is integrating host-to-host ERP capabilities for automated enterprise payments while broadening agency banking beyond basic deposits and cash transactions.
Beyond operational convenience, this digital overhaul serves rural and peri-urban markets by expanding access and simplifying execution. By making its architecture interoperable with third-party innovators, Faulu MFB connects customers to sector-specific solutions, such as enabling farmers to access specialized credit facilities and agri-input ecosystems through a single platform.
Ultimately, the lender’s strategy positions technology as an integrated ecosystem rather than an alternative channel to brick-and-mortar, establishing a unified gateway for digital MSME financial services.
Credit designed around the business, not the calendar
Agriculture and trade finance highlight why rigid credit structures often fail small enterprises. Farmers and livestock producers operate around production cycles, weather, and market access rather than fixed monthly calendars, requiring feed, breeding, and input investments long before sales generate cash flow.
Faulu MFB addresses this gap by aligning credit structures with actual cash-flow dynamics. In livestock, facilities for breeding and fattening incorporate bullet payments, deferring repayment until animals reach market. The same principle applies to trade finance, where underwriting and maturity dates match supplier payment terms to protect businesses from artificial liquidity crunches.
This approach marks a fundamental shift in MSMEs lending philosophy: adapting product structures to fit the customer’s business cycle rather than forcing irregular cash flows into rigid corporate templates.
Making risk more understandable
Faulu MFB applies this philosophy directly to agricultural finance, where weather volatility traditionally deters conservative lenders. Rather than avoiding sector risk, the bank uses irrigation-related products, crop insurance, and strategic tech partnerships to evaluate and structure credit better.
A key driver is the integration of alternative data to model crop performance and yield outcomes. As Mr. Ouma notes, the objective is not to eliminate risk entirely, but to understand it better. By replacing information asymmetry with data-driven underwriting, Faulu MFB transforms traditionally excluded farmers and agri-enterprises into assessable, financeable businesses.
From borrowing to financial wellness
Faulu MFB’s interpretation of financial inclusion extends well beyond credit disbursement. Through its association with the Old Mutual Foundation, the institution integrates financial literacy into a broader wellness framework, guiding customers through business assessment, cash flow management, savings, and responsible borrowing.
This approach reflects a core premise: capital access alone does not guarantee financial resilience. To build lasting stability, Faulu MFB embeds education directly into its customers’ engagement model, ensuring that they learn to manage and invest existing resources before taking on debt.
The institution’s mass-market money market fund (MMF) product is a central pillar of this strategy. By lowering the barrier-to-entry for retail investors, Faulu MFB enforces a deliberate sequence. In this regard, the lender encourages disciplined savings and investment first, then structure credit around the customer’s actual capacity. The result is a model that treats financial inclusion as a long-term development journey rather than a single transaction.
Keeping the entrepreneur on the journey
Historically, one of the primary challenges in MSME finance has been keeping pace with successful enterprises. As microfinance customers scale, their transactional and capital requirements become more sophisticated, frequently driving them toward mainstream lenders.
Faulu MFB faced this particular challenge in the past, where legacy payment and digital banking systems limited its ability to retain high-growth customers. To address this, Faulu has expanded its transactional, payment, and collection infrastructure while raising its lending capacity to upwards of Kshs. 50 million.
This enhancement directly supports Faulu MFB’s positioning as a comprehensive digital MSME bank. Rather than acting solely as an entry point for emerging borrowers, the institution is now structured to accompany enterprises across every growth stage, ensuring its financing capacity and technology evolve at the same pace as its clients.
Redefining what the market knows about Faulu MFB
The institution’s renewed MSME campaign is partly driven by a perception challenge. Faulu MFB is already well known in the Kenyan market, but Mr. Ouma says that recognition has historically been associated with micro and group lending. That perception does not fully reflect the breadth of services now available to MSMEs, including trade finance, foreign exchange, international payments, local payments and larger-ticket financing.
The campaign therefore seeks to close the gap between brand awareness and product understanding. That is an important distinction. A financial institution can be highly recognisable and still have customers who do not know the full range of its products and services offering.
For Faulu MFB, changing that perception is part of the transformation itself. The institution is not abandoning its microfinance heritage. On the contrary, it is attempting to build upon the knowledge accumulated from serving smaller enterprises while expanding its ability to finance their next stages of growth.
Digitising the community lending model
That evolution is also visible in Faulu MFB’s approach to group lending. The institution continues to recognise the relevance of the Grameen model and community-based lending, but it is digitalising the process. Groups can increasingly self-onboard, establish identities, reconcile transactions and create greater visibility around their financial activities through technology. This is particularly relevant because many groups operating in Kenya are informal. Requiring every group to navigate lengthy formalisation processes can create a barrier to financial access.
Faulu MFB’s approach is to simplify the journey while maintaining the necessary identification and governance requirements. The group officials can be identified, minutes of the meetings can be documented and accounts established through lighter know your customer (KYC) processes, while individual members can subsequently create digital KYC accounts. At the same time, the lender is exploring digital micro-lending using alternative data sources to assess customers at scale.
The bigger question
Faulu MFB’s strategy is ultimately responding to a structural problem. Most of the challenges faced by MSMEs are not addressed easily by mainstream lenders targeting business from corporates. These challenges according to Mr. Ouma include: data availability, the quality of collateral and the appetite of financial institutions to lend to MSMEs. The implication is that the financing gap cannot be addressed simply by increasing the amount of capital available. Financial institutions must also improve how they assess businesses and how they structure the financing offered to them.
For Faulu MFB, technology provides part of that answer. It can reduce the friction associated with onboarding, improve access to transactional services, support alternative-data underwriting and bring different financial solutions closer to the customer. But technology is being paired with another element that has been part of Faulu MFB’s proposition for years: an understanding of the realities of micro and small businesses.
As Mr. Ouma puts it, when advising customers, the choice of a financial partner should be based on whether the institution understands their needs and can provide an accessible and flexible relationship.
The marker of transformation
This recognition highlights Faulu MFB’s deliberate repositioning around the evolving needs of MSMEs. Its strategy aggregates larger-ticket facilities, cash-flow-based products, digital banking, agricultural risk assessment, group lending, and financial literacy solutions into an unified framework.
The strategy’s significance lies in its integration, delivering end-to-end support that scales alongside growing enterprises. For an institution executing a major digital transformation, the IFIA – 2026 award validates its pivot toward becoming a premier digital MSME microfinance bank.
Focus now shifts to execution: leveraging technology to lower borrowing costs, expand access, and equip entrepreneurs with management and risk tools. Ultimately, Faulu MFB’s proposition reflects a broader shift in Kenya’s financial landscape, where true inclusion is measured not merely by account creation, but by the long-term productivity and growth of the enterprise.