


Recognised as 1st Runner-Up for Microfinance Bank of the Year and 2nd Runner-Up for Fastest Growing Microfinance Bank at the 2026 IFIA Awards, Muungano is translating its community roots into a broader financial services model anchored in agriculture, MSMEs, digital delivery and disciplined growth

Muungano Microfinance Bank’s recognition at the 2026 Inclusive Finance Industry Awards comes at a defining stage in the institution’s evolution. Named first runner-up in the Microfinance Bank of the Year and second runner-up in the Fastest Growing Microfinance Bank categories, the bank’s performance reflects a strategy that has combined community proximity with productive-sector financing, stronger delivery channels and measured institutional expansion.
The recognition is particularly significant because Muungano MFB was deliberately built outside Kenya’s traditional urban banking centres. Headquartered in Kangari, Kigumo Sub-County, Murang’a County, it became the first microfinance bank to establish its headquarters in a rural setting, placing proximity to the communities it was created to serve at the centre of its operating model.
Established from a community-based foundation, Muungano began with a strong emphasis on agriculture, particularly the dairy and tea value chains, before broadening its reach to retail businesses, entrepreneurs, MSMEs and individual borrowers. Its evolution has been accompanied by a significant change in institutional scale. The lender started with a community licence in 2020, acquired a nationwide licence in 2024 and has since grown to five brick-and-mortar branches alongside its digital Muungano Popote channel.
The trajectory is also visible on the balance sheet. Muungano MFB’s asset base grew from about Kshs. 131.9 million in 2020 to Kshs. 694.5 million in 2025, while net loans and advances increased from Kshs. 28.9 million to Kshs. 501.1 million over the same period. Additionally, customer deposits rose from Kshs. 47.4 million to approximately Kshs. 290.1 million.
This is the institutional backdrop against which the IFIA recognition sits: a young microfinance bank expanding from a community-oriented financial institution into a broader microfinance platform without abandoning the market understanding that shaped its beginnings.
Financing the real the economy
Muungano MFB’s product architecture is deliberately tied to the economic activities of its customers. Its portfolio covers deposits and savings, credit and digital financial services, serving smallholder farmers, MSMEs, entrepreneurs, salaried individuals, retail businesses, groups(chamas) and associations.
On the lending side, the bank offers business financing, asset financing, agricultural financing, rental-property financing and personal financing, while its savings proposition includes current accounts, flexible savings, fixed deposits, junior savings and investment accounts for groups and associations.
Agriculture, however, remains one of its defining areas of specialisation. Muungano MFB’s agricultural portfolio has evolved into a broader value-chain proposition through products including Maziwa Boost for dairy farming, Majani Boost for tea, Avocado Boost for avocadoes and Kuku Boost for poultry.
This is significant because the bank does not view agricultural finance as a transaction between a lender and an individual farmer alone. Its stated approach is to understand the wider ecosystem around production, aggregation, processing and marketing, allowing financial services to reach multiple points along a value chain.
The institution’s portfolio has also changed materially just as its market has evolved. From an earlier mix heavily weighted towards agribusiness, its business now comprises approximately 30 per cent agribusiness, 55 per cent SMEs and 15 per cent personal lending, according to its company profile.
That shift demonstrates a widening institutional proposition. Agriculture remains foundational, but MSMEs have become increasingly central to the bank’s growth strategy, supported by products such as asset financing, boresha biashara, mradi (project) financing, retail business financing, vijana boost and rental boost.
Proximity as a business advantage
For Muungano MFB, community banking is more than a geographic designation. It is an operating advantage that enables the institution to understand local economic activity and build relationships in markets where financial institutions can otherwise be physically and institutionally distant from customers.
That proximity is particularly relevant in agriculture and MSME finance, where understanding the business behind a financing request can be as important as the financial information presented on paper.
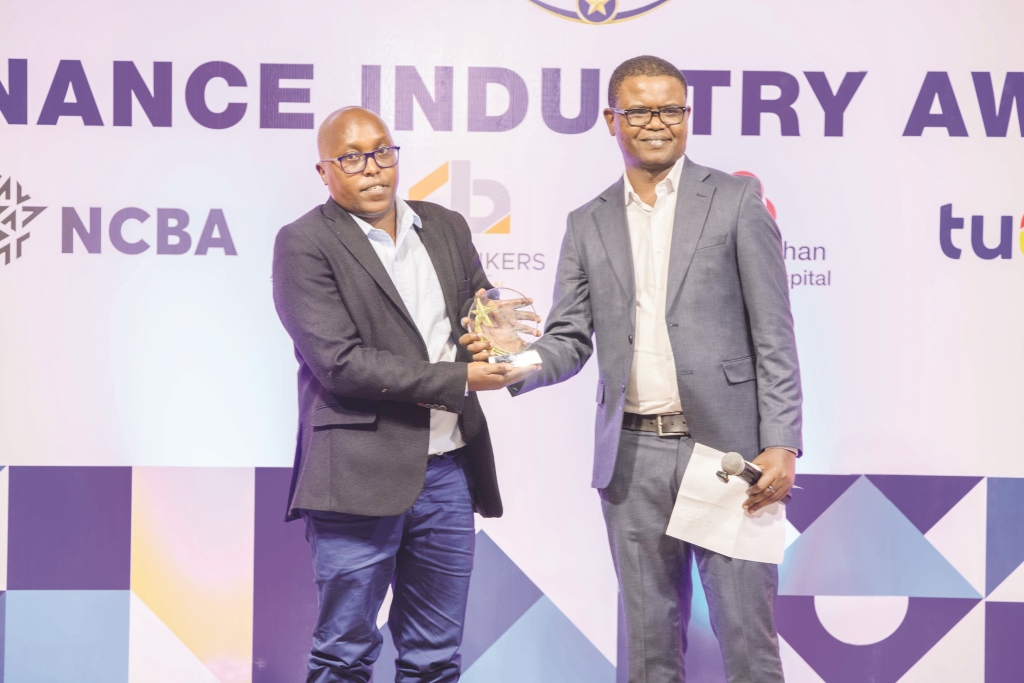
Mr. Anthony Mwangi, Business Development Manager, Muungano Microfinance Bank receiving an award during IFIA 2026.
Muungano MFB’s approach is therefore built around listening to customers and using what it learns to identify emerging needs, develop relevant products, establish partnerships and pursue new market opportunities. The lender describes this as an ongoing business-development responsibility: staying close to the market and continuously translating customers’ needs into sustainable financial solutions.
The same principle underpins its definition of financial inclusion. For Muungano MFB, access to a bank account or loan is only the beginning. The more important question is what that financial access produces afterwards.Does a farmer become more productive? Does an entrepreneur expand? Does an MSME create employment? Does a household become more financially resilient?
That outcome-oriented perspective provides a deeper context for the institution’s IFIA recognition. Its proposition is not simply to extend financial services to underserved markets, but to connect finance with the economic activity those customers are trying to build.
Growth with discipline
The second runner-up recognition for Fastest Growing Microfinance Bank provides another dimension to Muungano MFB’s story. The bank’s growth has been accompanied by a transition from a start-up institution into a more established player within Kenya’s microfinance sector. Its company profile records that the institution moved from the small to medium segment of the microfinance sector in 2024 and transitioned from making losses during its early years to recording profits in 2023 and again in 2025.
The financial trajectory illustrates that progression. After recording operating losses of Ksh14.6 million in 2020 and Ksh13.2 million in 2021, the bank’s performance improved substantially, reaching an operating profit of Ksh3.6 million in 2023. Although it recorded a loss in 2024, it returned to profitability in 2025 with an operating profit of approximately Ksh2.1 million, alongside total income of Ksh112.5 million.
For a growing financial institution, however, scale alone is not sufficient. Muungano MFB’s own response to the IFIA recognition emphasises the need to balance expansion with sound credit practices, portfolio quality, risk management, customer protection and regulatory compliance. That discipline will become increasingly important as the institution expands its customer base and deepens its presence in agricultural and MSME markets.
From brick and mortar to Muungano Popote
The microfinance bank’s physical network is increasingly being complemented by alternative delivery channels. Muungano MFB currently operates five brick-and-mortar branches in Kangari, Gatura, Ndunyu Chege, Delview and Kenol, alongside a Nairobi liaison office. Its digital Muungano Popoteplatform provides mobile banking services, enabling customers to access banking services beyond the physical branch network.
This combination reflects a broader strategic transition. Community banking provides the relationship, local presence and trust, while digital delivery offers greater convenience, accessibility and availability.
The lender’s own positioning—“Muungano Popote – Bank Anywhere Anytime”— captures that ambition: to extend the accessibility associated with its community model without requiring every customer interaction to take place inside a branch. For a growing institution, the significance of this transition extends beyond convenience. Digital and alternative channels provide a mechanism through which Muungano MFB can broaden its reach while keeping its physical footprint focused on markets where it can generate the strongest customer relationships and economic impact. “Our goal isn’t just to become a bigger bank, but a stronger and more trusted partner. Through Muungano Popote, we merge community-centred banking with modern accessibility, unlocking new opportunities across every value chain,” says Mr. Julius Mburu, Acting CEO, Muungano Microfinance Bank.
The next phase
Muungano plans to expand support for MSMEs and agricultural value chains while strengthening digital capabilities and developing partnerships with cooperatives, farmer organisations, MSMEs, business associations and other value-chain participants. Such partnerships can allow the institution to move beyond financing individual customers and participate more deeply in the ecosystems in which those customers operate.
The opportunity is particularly significant in value-chain finance. By understanding the relationships between farmers, traders, aggregators, processors and other businesses, Muungano MFB can identify points where financial services can unlock productivity and create broader economic value.
That strategy also changes the way the institution views its own growth. Muungano MFB’s stated ambition is not simply to become a larger financial institution, but a stronger, more trusted and more impactful financial partner.
Its commitment to impact is already reflected beyond lending through initiatives in financial literacy, community greening, social empowerment and physical and mental wellness, while the institution identifies employment creation and community development among the outcomes of its growth.
For Muungano, the IFIA recognition is therefore less an endpoint than a measure of how far its community-rooted model has travelled.The institution now has the opportunity to take that model into a larger market without losing the proximity that gave it relevance in the first place. Its challenge — and its opportunity — will be to scale products, partnerships and digital capabilities while maintaining the governance, responsible lending and customer understanding required to grow sustainably.
That collective foundation may ultimately prove as important as the growth figures. Because for a microfinance bank that began by placing itself deliberately within a rural community, the measure of scale is not simply how large the institution becomes, but how effectively it can continue turning financial access into productive opportunity.


