


Kenya has spent the better part of the last two decades expanding access to finance. With 84.8 per cent of adults accessing formal financial services in 2024, the country has established one of Africa’s most advanced financial inclusion ecosystems. But as access broadens, the central question facing the financial sector is changing.
What happens after access?
For Momentum Credit, the answer lies in moving beyond the traditional measurement of inclusion through accounts opened, loans disbursed or transactions completed. The most pertinent measure is what customers are ultimately able to do with their finances. Whether they can build businesses, manage working-capital pressures, acquire productive assets, withstand unexpected costs, create employment and pursue opportunities that would otherwise remain out of reach.
This distinction is increasingly important in an economy where households and businesses continue to navigate pressure on disposable income, operating costs and cash flow. A trader may have customers but lack the liquidity required to replenish stock. An entrepreneur may identify an opportunity but lack the capital to act on it. A school may have predictable enrolment but experience temporary liquidity pressure between fee cycles. A vehicle owner may possess a productive asset while simultaneously facing an urgent financial requirement.
These situations reveal that financial exclusion is not always about being completely outside the financial system. It can also be about having access to financial services that are poorly matched to the timing, structure or purpose of a customer’s need.
It is within this changing landscape that Momentum Credit has developed its proposition. Established in 2017, the institution set out with the conviction that financial access should expand possibilities rather than constrain them. Over the years, it has evolved from being predominantly associated with logbook financing into a broader financial-solutions business serving personal, business and asset-backed financing needs. Its customer base includes: entrepreneurs, small and medium enterprises (SMEs) owner managers, vehicle owners, civil servants and salaried professionals seeking flexible financing for working capital, immediate needs, investment opportunities and personal milestones.
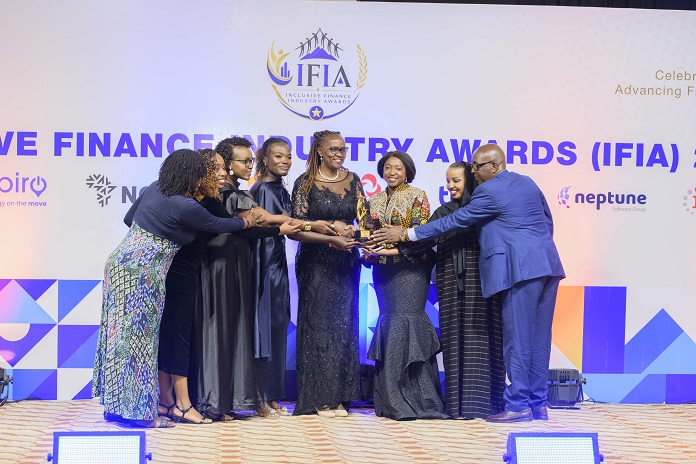
That evolution was recognised at the inaugural Inclusive Finance Industry Awards – 2026, where Momentum Credit was named first runner-up in the Non-Deposit Taking Credit Provider of the Year category. The recognition provides a useful lens through which to examine the institution’s wider transformation, from a business centred primarily on logbook financing to one seeking to respond to a wide range of customer needs through product diversification, digitalisation and customer-focused delivery.
The Recognition
For Momentum Credit’s leadership, the recognition reflects an approach built around customer experience, innovation, execution and people. “We have continued to improve how customers access and experience our solutions,” Yvonne Asang’re-Ochieng’, the Managing Director says, pointing to product development, technology, alternative access channels, turnaround times and efforts to make the customer journey simpler and clearer.
She identifies four elements behind the institution’s performance: customer obsession, continuous innovation, disciplined execution and talent. Importantly, the award is described as a collective achievement rather than the product of one function within the organisation.
The significance of this perspective is that inclusive finance ultimately depends on the quality of the entire delivery chain. A product can be appropriately designed, but its usefulness to the customer depends on how efficiently it can be accessed, assessed, processed and serviced.
Momentum Credit’s recognition therefore sits within a broader institutional transition: the attempt to build financial solutions around the actual economic lives of customers rather than fitting them into rigid financing structures.
Unlocking value from productive assets
Momentum Credit’s flagship offering remains logbook financing, a product that illustrates this philosophy very clearly. This solution allows customers to access value held in their motor vehicles while continuing to use the asset. For many entrepreneurs and other vehicle owners, that distinction is significant because a vehicle can simultaneously function as an asset, a tool of trade, a source of income and an enabler of mobility.
Unlocking capital against such an asset can therefore serve purposes extending beyond the vehicle itself. The capital may be directed towards restocking a business, expanding operations, meeting school-fee obligations, responding to an emergency or pursuing an opportunity.
This is where asset-backed finance takes on a wider financial-inclusion role. The underlying proposition is not simply to lend against a vehicle, but to allow an existing productive asset to continue supporting economic activities while also providing access to liquidity.
The approach reflects Momentum Credit’s broader belief that financing should be connected to the customer’s objective. “We do not want to provide financing for financing’s sake,” Yvonne explains. “We want to understand what the customer is trying to achieve and build solutions that help make that possible.”
The rise of responsive digital credit
The same philosophy is being applied to digital finance. Kenya’s financial ecosystem has become increasingly shaped by mobile technology, with approximately 53.4 million active mobile-money subscriptions and smartphones accounting for 63.7 per cent of connected mobile devices, according to Yvonne. The scale of this infrastructure creates opportunities for financial institutions to make services faster, simpler and more accessible.
Through the Ezua Chapaa product, the institution is responding to the reality of customers whose financing needs can arise between conventional borrowing cycles. The product provides revolving digital finance intended to give customers greater flexibility when short-term needs and opportunities emerge.
When financial access is embedded into a customer’s actual cash-flow requirements, digital infrastructure can make financing more responsive to the rhythm of small-businesses and household activities.
This distinction is particularly relevant to small and medium enterprises (SMEs) , where liquidity pressures can emerge quickly. Stock opportunities, operating expenses and short-term gaps do not necessarily wait for conventional financing timelines.
Momentum Credit’s strategy is explicitly digital-first, not digital-only. The lender believes that the future of financial services will require the efficiency of technology alongside trusted human relationships.
Capital for Women Building Businesses
SMEs remain central to Kenya’s economic structure, accounting for approximately 90 per cent of businesses and supporting more than 15 million jobs, according to the figures presented in the base material. Yet access to appropriate financing remains a constraint on their ability to expand.
For women entrepreneurs in particular, the relevance of appropriately structured SMEs finance extends beyond the provision of working capital. Financing can determine whether an enterprise can purchase stock, acquire equipment, fulfil a contract, improve its operations, establish another location or create an additional job.
Momentum’s SME Financing proposition is positioned within this wider reality.
Rather than treating SME credit as a generic product, the institution’s stated approach is to understand the purpose for which the customer requires capital. That can mean financing inventory, equipment, expansion or other business needs.
The economic effect can extend beyond the borrower. A growing business purchases from suppliers, engages service providers and creates employment. The resulting activity supports a broader network of economic participation.This is particularly significant for young entrepreneurs entering sectors ranging from technology and agriculture to retail, transport, e-commerce, professional services and the creative economy. For such businesses, appropriately timed capital can help convert an opportunity into an operating enterprise.
Responsible lending as the foundation of scale
As the financial sector becomes increasingly digital, the question of responsible lending becomes inseparable from innovation. Yvonne argues that speed alone should not define financial innovation. Instead, responsible innovation should improve customer outcomes through transparency, appropriate lending, data protection, education and meaningful support.
This position is important because the expansion of digital access creates both opportunity and responsibility. Faster access to credit can help customers manage immediate needs, but the quality of that access depends on whether the financing is appropriate to the customer’s circumstances and purpose.
Momentum Credit’s institutional evolution has therefore placed customer experience, technology, operational excellence and regulatory maturity alongside product diversification. The Managing Director describes the last five years as a period that has fundamentally changed the shape of the organisation, with the business moving beyond its historic association with logbook financing to serve a wider range of customers and financial needs.
For a non-deposit-taking credit provider, this balance is particularly important. Sustainable expansion requires more than just increasing the number of customers or products. It requires the institution to maintain customers’ trust, while ensuring that growth is supported by appropriate systems, people, technology and risk management.
A financial partner
The clearest indication of Momentum Credit’s strategic direction is perhaps its ambition to change the relationship between the institution and its customers. Yvonne describes the transformation as a movement from being “a place customers come to borrow” towards becoming “a trusted financial partner they can grow with.”
A customer relationship built around a single transaction measures success through disbursement and repayment. A relationship built around the customer’s broader financial journey requires an institution to understand changing needs and develop solutions accordingly. This is reflected in Momentum Credit’s expanding product portfolio and its investment in digital transformation, customer experience and alternative access channels. It is also reflected in the lender’s emphasis on the human dimension of financial services.
Her description of the institution as digital-first, not digital-only captures this balance. Technology can simplify access and improve efficiency, but trust, understanding and customer relationships remain important components of financial service delivery.
The Next Horizon
Momentum Credit’s future strategy is therefore not framed simply around providing more products. Its stated ambition is to become more relevant across customers’ financial journeys while continuing to invest in technology, customer experience, responsible innovation, partnerships and solutions supporting Kenya’s growing SME economy.
That ambition reflects a broader transition taking place across the financial sector.Kenya has already demonstrated that financial access can be expanded at significant scale. The next phase is more demanding: ensuring that the services being accessed actually help customers become more resilient, productive and capable of progressing.
For Momentum Credit, it means a vehicle can remain productive while unlocking liquidity. It means digital credit can respond more flexibly to short-term business needs. It means SME financing can support stock, equipment, contracts and expansion. And it means innovation must remain connected to transparency, appropriate lending, customer protection and trust.
The institution’s IFIA – 2026 recognition arrives against this backdrop. For Momentum Credit , being named first runner-up in the Non- Deposit Taking Credit Provider of the Year category is a milestone, but its own leadership views recognition as creating another responsibility: to continue raising the standard.“Recognition creates expectation,” Yvonne avers.
That expectation sits at the heart of the next chapter.Because the future of inclusive finance will not ultimately be determined by how many people can access credit. It will be shaped by how effectively that credit helps people build, businesses grow and opportunities become achievable.

